China built the world's most advanced central bank digital currency and a cross-border rail that could route around the dollar. A hype-free explainer on the e-CNY, mBridge, and why the 'BRICS beats SWIFT' headline needs an asterisk.
There's a version of the digital-yuan story that's all geopolitics — a grand plan to dethrone the dollar — and a version that's all technology — a slightly faster way to pay for noodles. The truth I keep landing on is that it's both and neither: China has built the world's most advanced central bank digital currency, it's quietly wiring a cross-border settlement network that could route around Western payment rails, and it's also running into the same awkward question every CBDC hits — do ordinary people actually want government money on their phone? Here's my honest, hype-free read on what China's e-CNY is, what "mBridge" is, and why the BRICS-bypasses-SWIFT headline needs an asterisk.
A CBDC is central-bank money in digital form — a direct claim on the state, not a bank deposit. Illustration by Aliteq. · Illustration by Aliteq / generated with Higgsfield
What a CBDC actually is
Money on your phone already feels digital, so people ask why a CBDC matters. The difference is who owes you. The balance in your banking app is a claim on a commercial bank. A CBDC is a claim on the central bank itself — the digital equivalent of physical cash, issued by the state. That changes things: it can settle instantly with no intermediary, it can be programmed (with all the promise and the surveillance worries that implies), and it gives a government a direct rail into the economy. China's version is the e-CNY, and it's the furthest along of any major economy.
On raw numbers the e-CNY is huge — the largest CBDC pilot anywhere, with billions of retail transactions worth trillions of yuan cumulatively. But there's a twist worth noting: in early 2026 the People's Bank of China reclassified the e-CNY in a way that reads more like a bank deposit than digital cash, and everyday adoption has lagged the headline volumes — a lot of usage has been government-nudged rather than organic. Even the world leader is discovering that building a CBDC is easier than getting people to prefer it.
World's largest
e-CNY status
CBDC pilot by volume
~$55B
mBridge settled
cumulative cross-border
~95%
Yuan share of mBridge
of settlement volume
To 2030
In China's plan
incl. a yield-paying CBDC
mBridge: the part that actually worries Washington
The domestic digital yuan is interesting; the cross-border piece is strategic. Project mBridge connects the central banks of several economies — mainland China, Hong Kong, Thailand, the UAE and others have been involved — on a shared platform that settles cross-border payments directly between them, in their own CBDCs, without routing through the correspondent-banking and dollar system. It has settled thousands of transactions worth tens of billions of dollars, and China's digital yuan is by far the dominant currency on it. If you want the one-line reason the US and Europe are paying attention: mBridge is a live proof-of-concept for moving serious money internationally without touching Western rails.
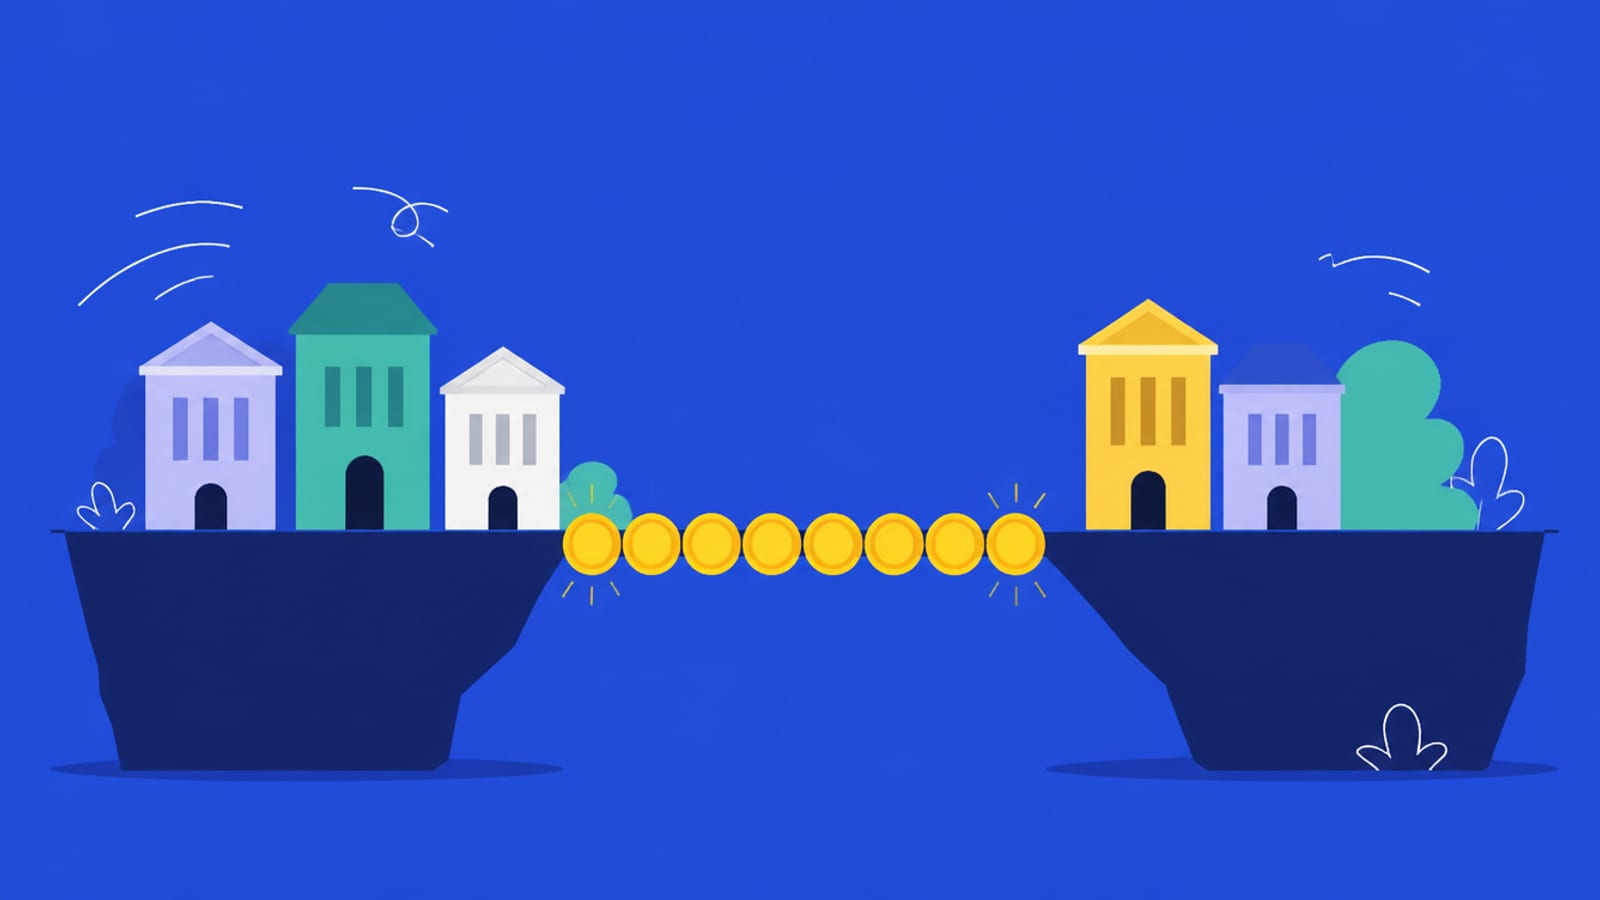
mBridge lets member central banks settle cross-border payments directly in their own CBDCs. Illustration by Aliteq. · Illustration by Aliteq / generated with Higgsfield
Where the headline gets it wrong
"BRICS builds a SWIFT-killer to dodge sanctions" makes a great headline and a shaky fact. Three caveats I always add. First, the BIS itself pushed back, with General Manager Agustín Carstens stating flatly that "mBridge is not the BRICS bridge" and that its systems can't be used by sanctioned states. Second, membership isn't monolithic — at least one participant has reportedly stepped back from the project. Third, scale: tens of billions of dollars is real, but it's a rounding error next to the trillions that move through the existing system daily. This is an important experiment, not a completed alternative.
Quick answers
How is a CBDC different from a stablecoin?
A CBDC is issued by a central bank and is a direct liability of the state. A stablecoin (like a dollar-pegged token) is issued by a private company and backed by reserves it holds. Both are digital money; the difference is who stands behind it and who controls it.
Is the digital yuan replacing cash in China?
Not really — it's the biggest CBDC pilot in the world by volume, but everyday adoption has lagged, and a lot of usage has been encouraged by the state rather than chosen by users. Even the leader is finding demand is the hard part.
Could this actually bypass the dollar and SWIFT?
In theory mBridge shows how; in practice it's small, the BIS has distanced itself from the sanctions-evasion framing, and displacing the dollar needs trust and scale that technology alone can't provide. It's a meaningful experiment, not an imminent replacement.
Should other countries join?
That's a sovereign policy question with real trade-offs — efficiency and independence from Western rails on one side, dependence on a China-led system and surveillance concerns on the other. There's no neutral 'yes' or 'no'; it depends on a country's politics and priorities.
CBDCs are the public side of digitising money; the private-market side is tokenizing real assets like bonds and property. I cover that in my companion explainer on real-world asset tokenization and where US rules stand. Read together, they're the two big bets on what money looks like when the ledger goes digital.
If it's the money-and-technology intersection that pulls you in, the other big lane we write about is the consumer one — how people use AI to earn. Start with how people make money with AI and the wider AI Money hub.